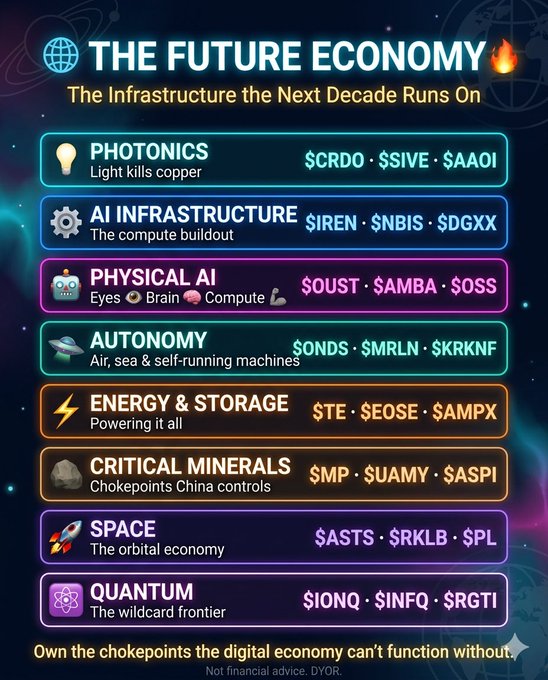
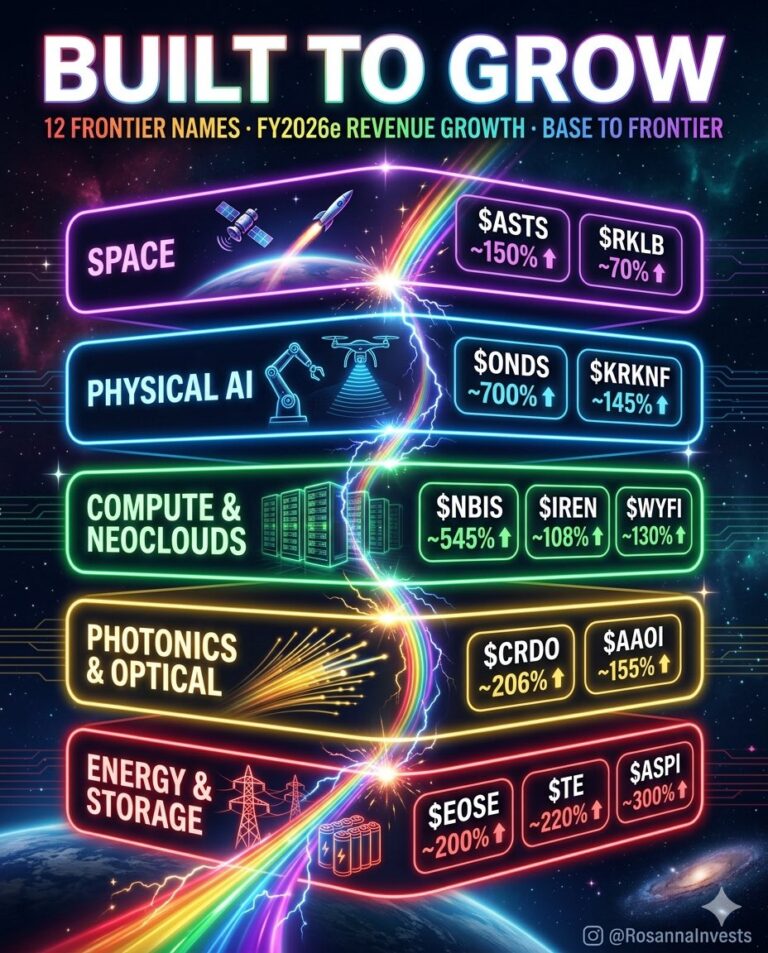
ASTS Is More Than a Space Story
The market often files AST SpaceMobile under space, but the customer is a phone with no signal. That framing misses the commercial infrastructure being built underneath the story.
The company has assembled nearly 60 carrier agreements representing more than three billion subscribers, including AT&T, Verizon, Vodafone, Orange, stc, Telefnica, and CK Hutchison. Those relationships matter because distribution is usually the hard part of a network business. A satellite can be technically impressive and still struggle if customers cannot access it through trusted carriers.
The investment case is therefore less about rockets and more about connectivity. Direct-to-device service can fill coverage gaps, improve resilience, and extend a carriers reach without requiring every location to receive a new terrestrial buildout. If execution holds, the addressable market is measured by subscribers and usagenot by how many launches make the news.
That does not remove risk. Capital intensity, spectrum, launch cadence, handset compatibility, and carrier economics all determine whether agreements become recurring revenue. But the filings show a business with a distribution map that is much broader than the space stock label suggests.
The right question is not whether ASTS belongs in space. It is whether the company can convert that global carrier footprint into reliable, profitable service.