FLNC Options Flow: Paid to Wait, Willing to Own
A large FLNC options trade offered a useful glimpse into how sophisticated capital can express a long thesis without simply chasing shares.
The structure involved roughly $19 million of premium: puts sold, a straddle sold to open, and $30 calls bought. The common thread is willingness to own the stock at $30 while being paid to wait. That is very different from a one-way lottery-ticket call purchase.
Options flow is not a crystal ball. A trade can be part of a spread, a hedge, or a larger portfolio. But the structure still tells us what risk someone is willing to warehouse. Selling downside premium suggests the trader is comfortable with assignment if the stock reaches the strike. Buying upside calls preserves participation if the operating thesis accelerates.
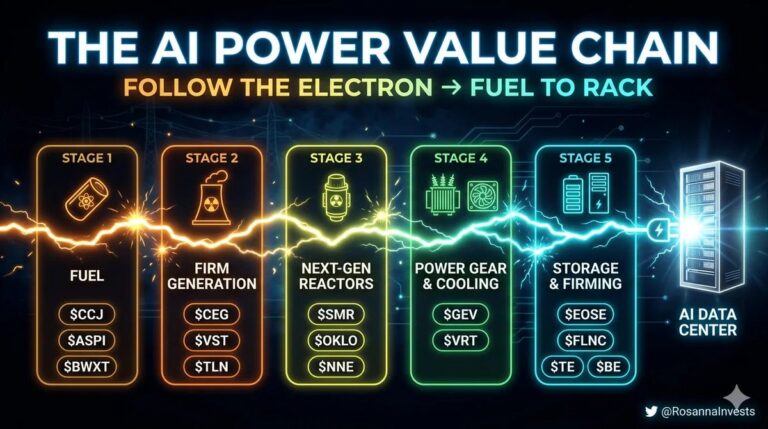
For investors, the important work is connecting the tape to the business. FLNC sits at the intersection of grid investment, storage demand, and the need to make intermittent generation usable. Those are long-cycle drivers, but execution and financing still matter.
The signal is therefore conditional: the flow is constructive if the company converts demand into backlog, margins, and cash. It is not a substitute for due diligence. The market is paying attention to the same bottleneck; the edge is understanding the terms on which capital is willing to wait.