The AI Trade Just Became a Credit Trade
The AI trade just became a credit trade
The four biggest buyers guided to roughly $730B of capex for 2026, up from about $410B in 2025.
Here’s what changed underneath it. In Q2, Alphabet’s capex ran past its operating cash flow and free cash flow went to negative $5.86B. First negative quarter since the 2004 IPO.
Goldman now has hyperscalers funding more than a third of 2027 capex with investment grade bonds. It was about a quarter in 2025.
That reprices the whole map.
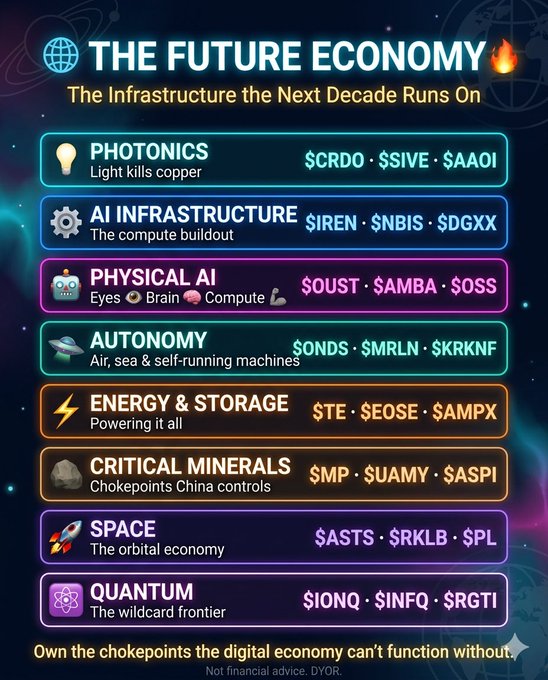
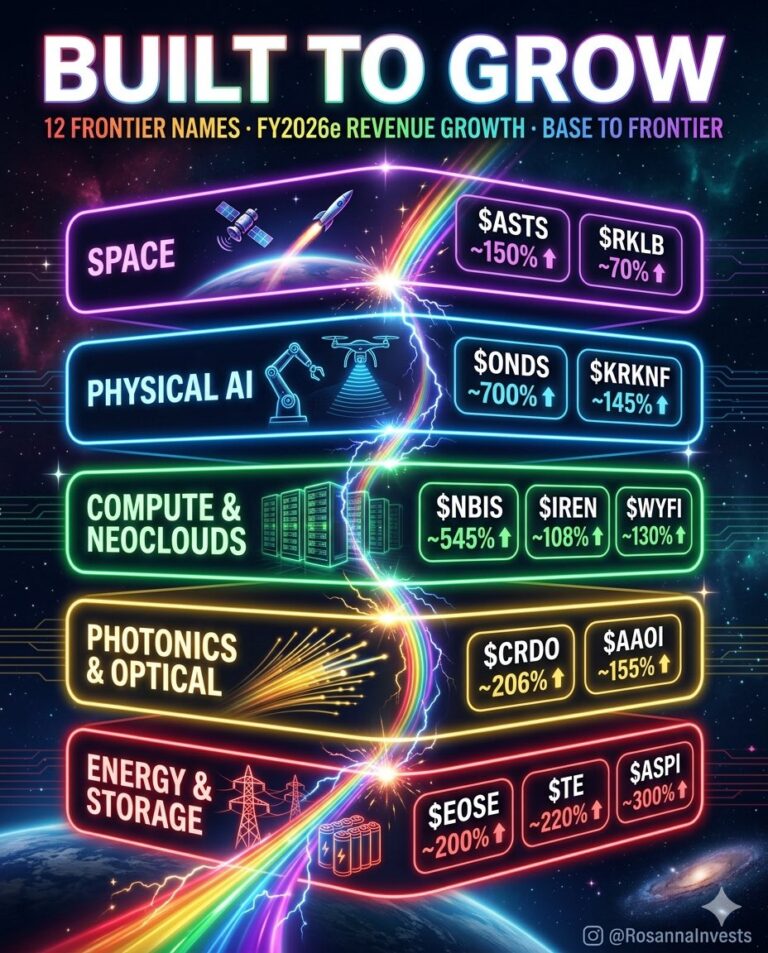
$NVDA $AVGO $MU $CRDO $LITE sell into that budget.
$IREN $NBIS $CIFR sign contracts against it.
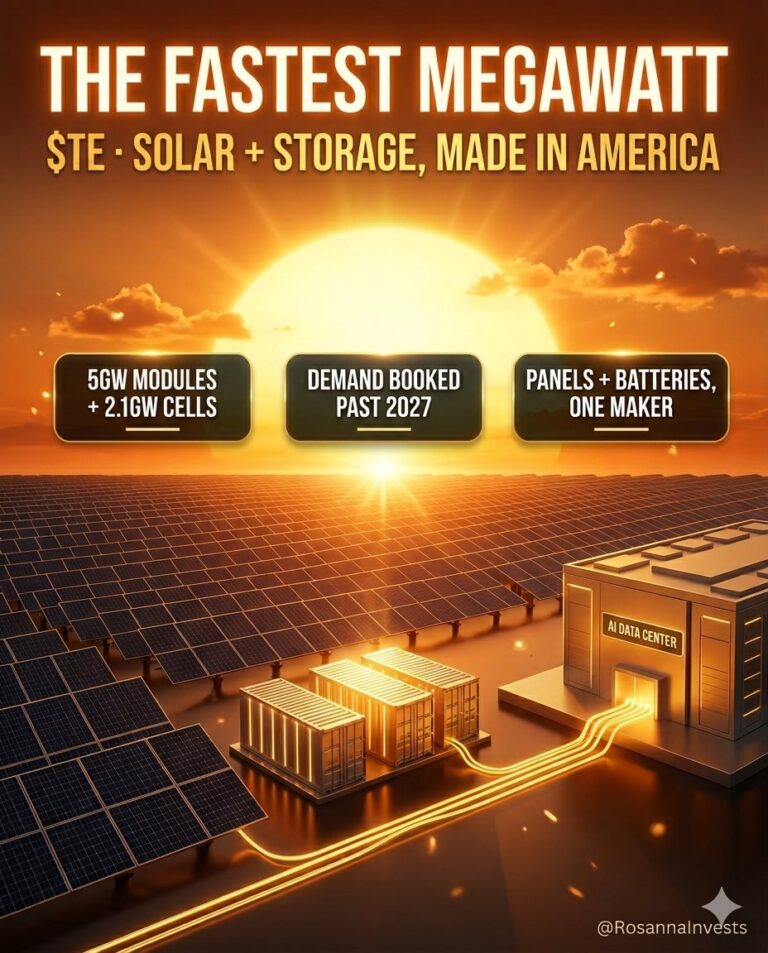
$VST $BE $TE get paid to power it.
When the buildout ran on cash flow the only question was demand. Now there’s a second one, and it’s spreads.
This isn’t the bubble argument. Bubbles run on stories and this still runs on contracts. But a contract funded with a bond fails differently than a contract funded with cash.
Watch the IG new issue calendar the way you watch the capex guide.