When the Index Holds and High-Beta Falls, Hedging Matters
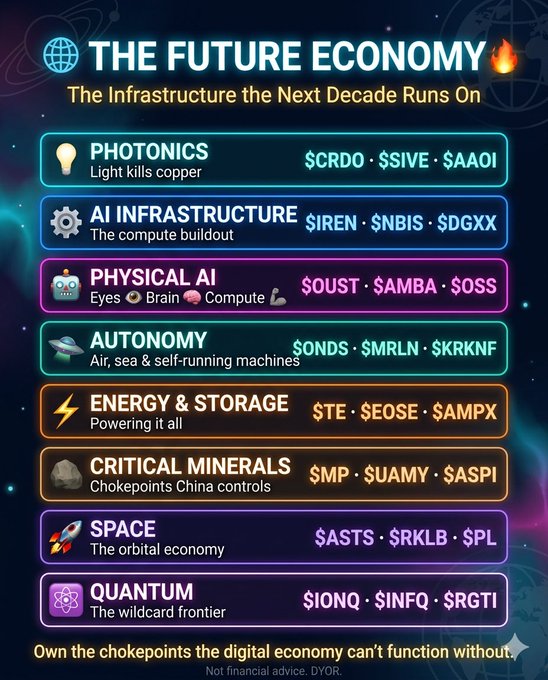
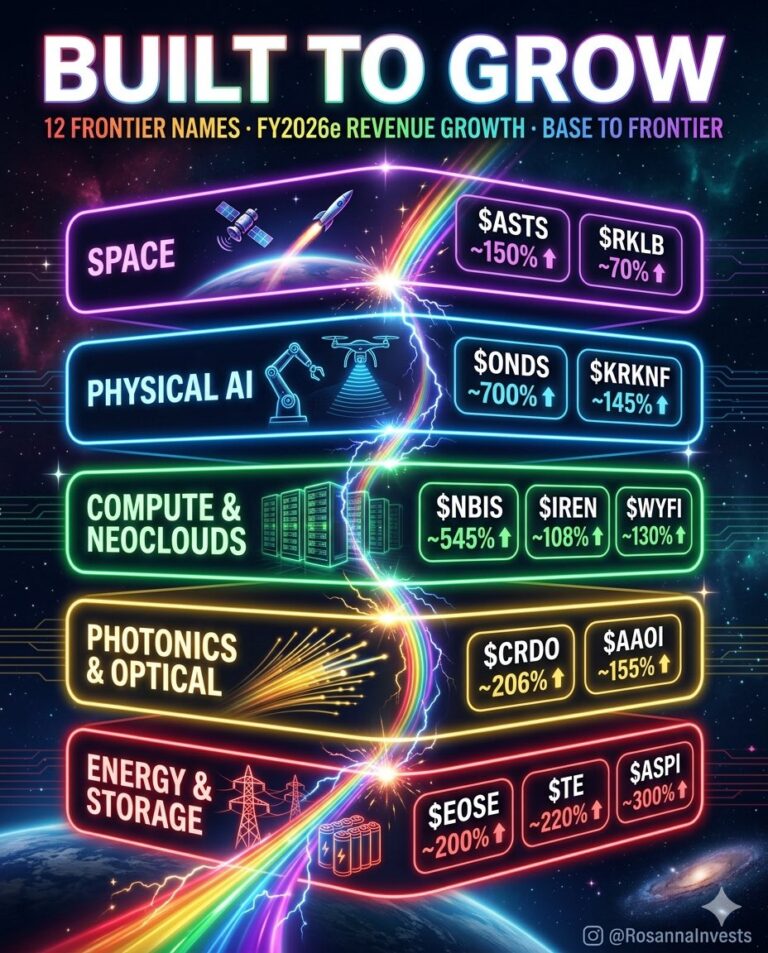
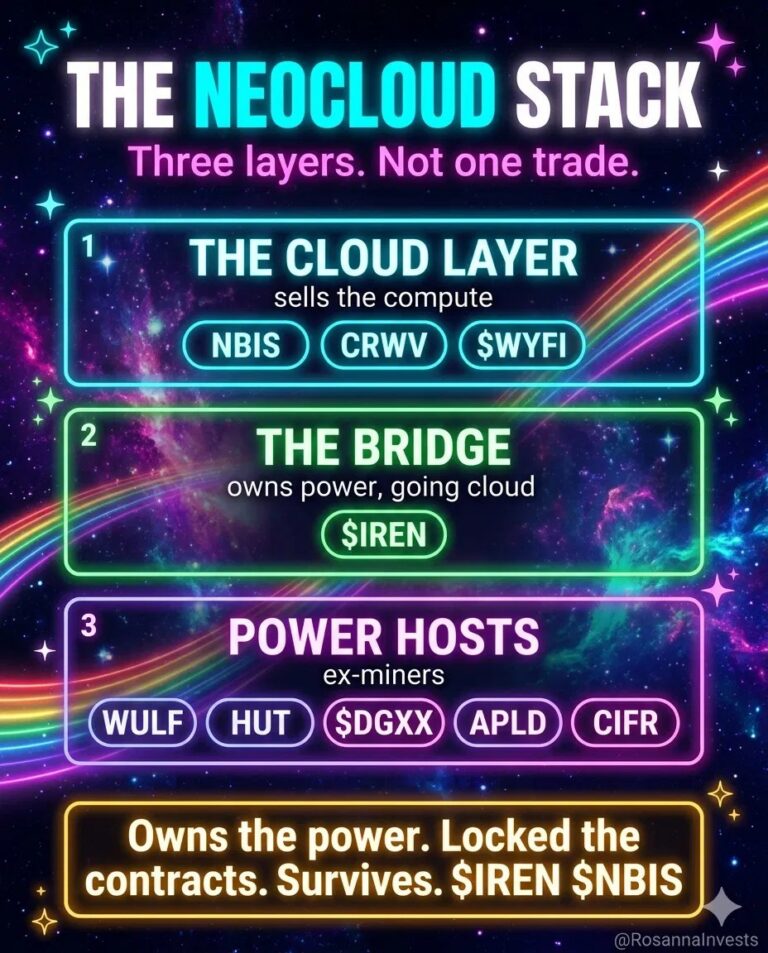
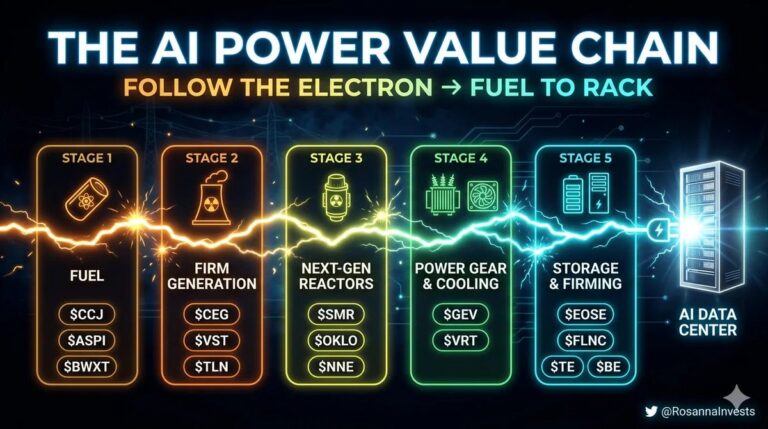
A market can look healthy from the index level while individual books are getting hit. This year has been a live experiment in hedging: the broad index barely moved while many high-beta AI names fell 30% to 50%.
That gap matters. When a portfolio is concentrated in high-growth companies, index stability is not protection. The factor exposure, valuation duration, and liquidity profile of the individual names can be completely different from the benchmark.
A simple hedge using index puts can buy time without forcing an investor to sell every long-term holding. It is not free insurance, and it should be sized deliberately, but the cost can be worthwhile when the book is exposed to a sharp volatility regime change.
The lesson is practical: measure the risk of the portfolio you actually own, not the index you watch. A calm headline index can coexist with a very uncomfortable high-beta drawdown.