IREN: Financing Is the Test, Not the Thesis
IREN’s latest financing question is less about whether the company can raise capital and more about what that capital buys.
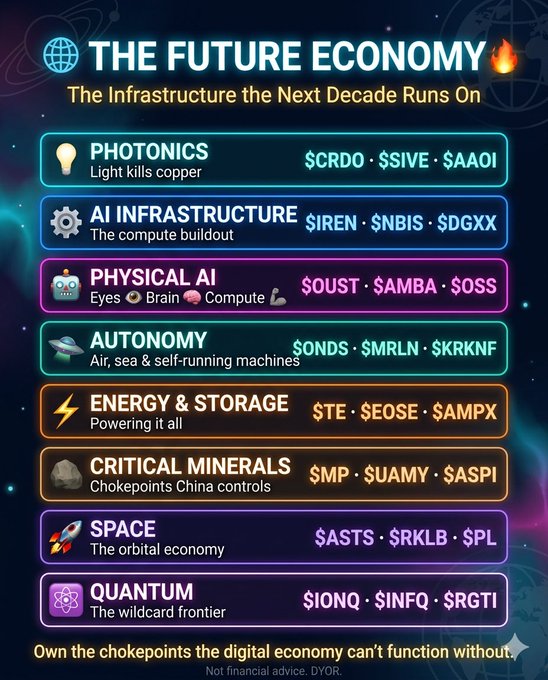
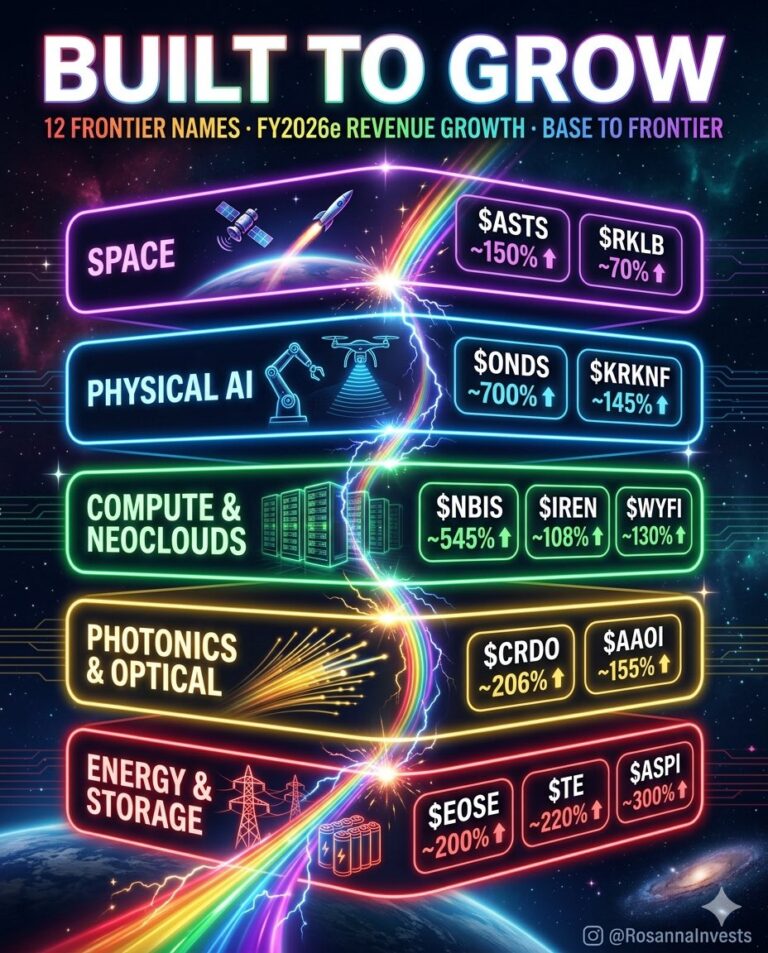
The bull case is not simply Bitcoin mining. IREN has spent years assembling power, land, and data-center capacity in places where electricity can be contracted and expanded. That infrastructure is now being repositioned for AI workloads, where signed capacity can command a different value than mining revenue alone.
But financing is the test. A capital raise can accelerate the buildout, yet it can also transfer too much of the upside to new investors if the terms are aggressive. The key variables are the price, the size of the raise, the use of proceeds, and whether the funding converts contracted capacity into revenue on schedule.
That is why I would separate the thesis from the transaction. The thesis is that scarce power and usable compute are valuable. The transaction determines how much of that value remains with existing shareholders.
Investors should watch dilution, debt service, and customer concentration alongside megawatts. A larger footprint is only useful if it is energized, connected, and monetized. IREN’s opportunity is real, but execution and financing discipline will decide whether the opportunity compounds for shareholders.
The right question is not whether IREN needs capital. It is whether each new dollar of capital increases the value of the platform by more than the value given away to fund it.