HydroGraph: the market chose its graphene champion
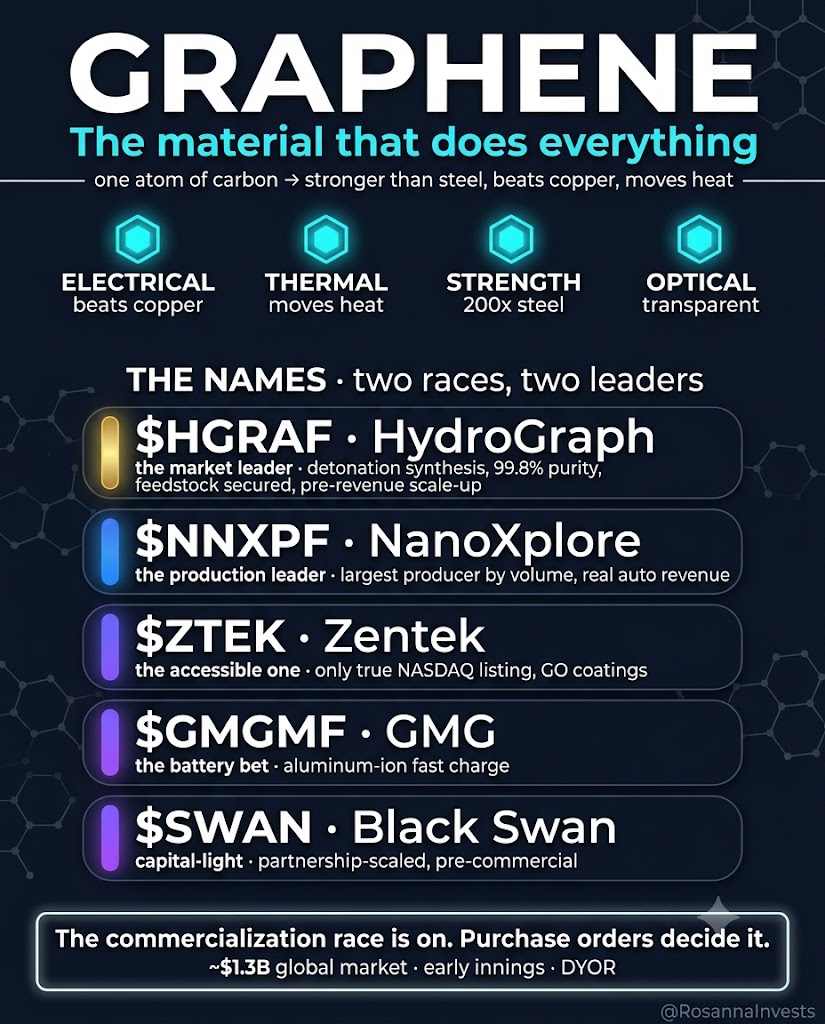
$HGRAF · HydroGraph · the market leader
The market chose its graphene champion this year: $0.15 to over $8, roughly a $1.5B cap. Here’s what it’s actually buying. Detonation synthesis builds graphene bottom-up from gas, with no graphite, no mine, and no Chinese supply chain. HydroGraph reports 99.8% purity, third-party verification, identical batches made in Texas, and US, UK and EU clearance for commercial sales.
The Western Gas deal locked the feedstock, $42.8M cash and near-zero debt provide room to execute, and more than 80 customers are engaged. The ledger still matters: trailing revenue is sixty-two thousand dollars. The float is near-totally retail, which is how you get a 30x and how you get the round trip. A NASDAQ uplisting changes who can buy the stock, not what the company earns.
The bull case is that HydroGraph has spent years solving the manufacturing problem. Expansion into Texas, modular production, dispersion products, and partnerships moving toward commercial coatings and polymers are meaningful developments. In an FEOC-driven supply chain, an American graphene producer could become more valuable than it would have been in a globalization-first world.
That does not mean $HGRAF wins. Revenue has to catch up with the story. Watch purchase orders, repeat customers, production tonnage, and gross margins, not just press releases. The investment question is simple: can they become the preferred supplier for coatings, batteries, polymers, aerospace and defense? If so, they could become enormous.