Economics
Economics · Investing
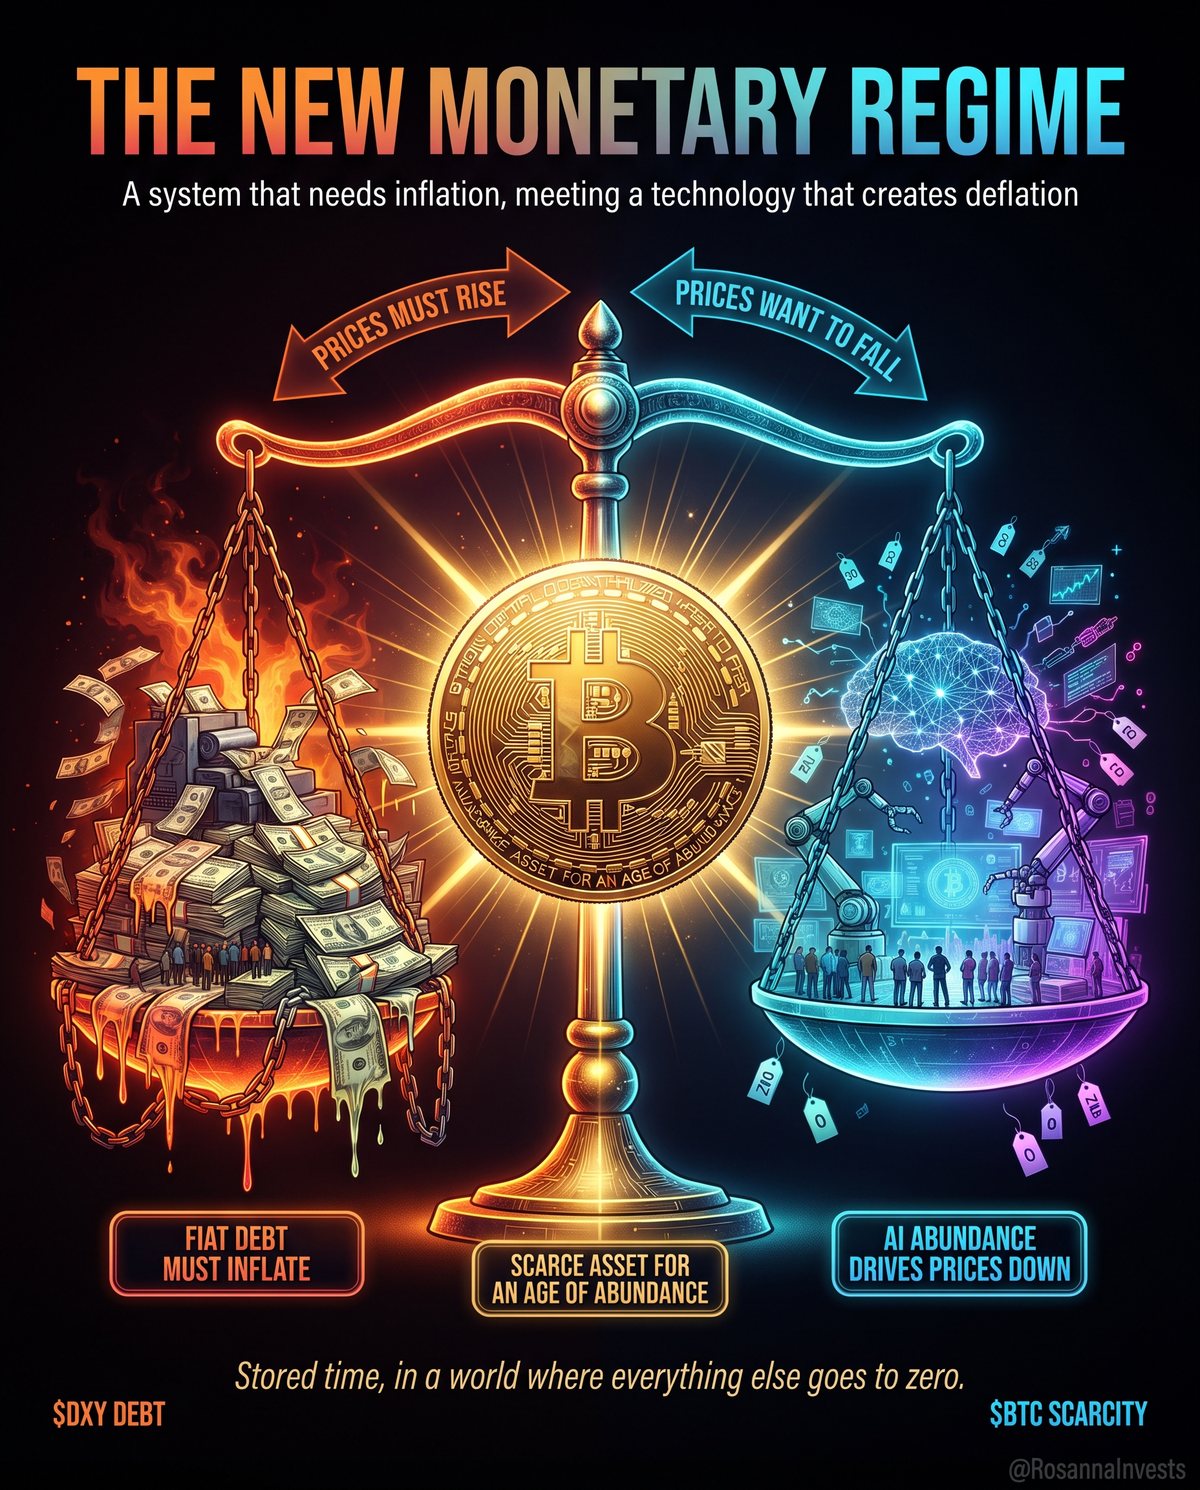
Why Bitcoin Gets Stronger As AI Wins
AI keeps lowering the cost of producing almost everything. A heavily indebted financial system cannot comfortably let that show up as broad deflation. Bitcoin is what sits between those two forces.
Read the article
Featured Categories
Popular Articles


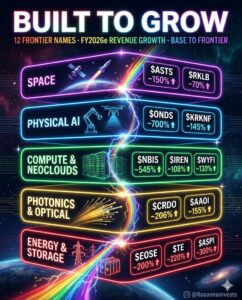
Built to grow: 12 companies and FY2026e revenue growth
Multiples don’t re-rate when the business changes


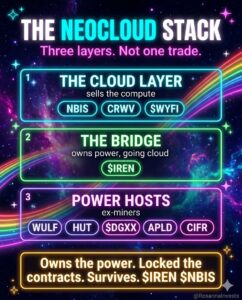
The neocloud stack: three layers, three different trades
A Negative GDP Print Driven by Tariff Front-Running
Is this negative GDP print an outlier due to front running of tariffs? Q1 GDP declines 0.3% SAAR as massive
Manufacturing recession beneath headline growth
There have been pockets of recessions in many sectors that have been growing. Manufacturing has been in a recession for
FED -> 50 bps RATE CUT & more to come
FED -> 50 bps RATE CUT & more to come 525-550 -> 475-500 With CPI already underestimating inflation & fake
NFIB August: Small Business Softness
NFIB August Small businesses matter! SBO Index FELL 2.5 pts (32 mo below 50 yr Ave) Uncertainty ROSE to 92
NFIB Small Business July Report
NFIB Small Business JULY Inflation is TOP concern. We are in a difficult middle range right now where DEMAND is
Public Debt: $35.123 Trillion
Public DEBT: $35.123T ~$1 trillion in new debt added every 100 days! >$36T likely by EOY Next 12m, + $1.5T
Are markets really forward looking as they are purported to be?
Are markets really forward looking as they are purported to be? IMO we have been in a “stealth” recession with
I can see first rate cuts in September. Why? Several reasons.
I can see first rate cuts in September. Why? Several reasons. R-G model challenging to go positive for massive debt
Growth Slowdown. Money Supply Contraction. Higher rates have massively tightened the lending side of money creation ~83% (FRB) reducing S&D of loans. Contraction impacting private sector (crowding out too) especially smaller businesses more sensitive to higher rates.
Growth Slowdown. Money Supply Contraction. Higher rates have massively tightened the lending side of money creation ~83% (FRB) reducing S&D
CPI April Report
CPI April Report CPI +.3% M/M, 3.4% Y/Y CORE .3% M/M, 3.6% Y/Y Are 3s the new 2s? If we
GDP Q1 2024: Incomplete Estimates and Seasonal Adjustments
GDP Q1 2024 (estimate incomplete & subj to revisions plus seasonally adj) *remember those 3 caveats! +1.6% (deceleration from 3.4%
Cut Too Soon: Lower Interest Expense, Refuel Inflation
Cut too soon – they lower their interest expense but trigger refueling inflation in addition to massive fiscal spending. Cut