Why Bitcoin Gets Stronger As AI Wins
The New Monetary Regime
We are living through a monetary regime change.
I don’t mean the dollar disappears or every contract gets rewritten in bitcoin one morning. Regimes don’t change that cleanly. The unit on the invoice stays the same while the rules around it move. Reserve preferences change before payment habits do. The marginal buyer of a sovereign bond changes before the currency on the bond does. Regime change begins when the constraints change.
Here’s the constraint that changed.
Technology reduces the amount of human time it takes to produce something. Good technology gives time back. Money has the opposite job. It carries forward the value of time already spent.
For most of history both jobs were done by things that leaked. Fiat leaks by design. Gold leaked into vaults. So when a technology arrives that gives back more time than any before it, the question is what you store the dividend in.
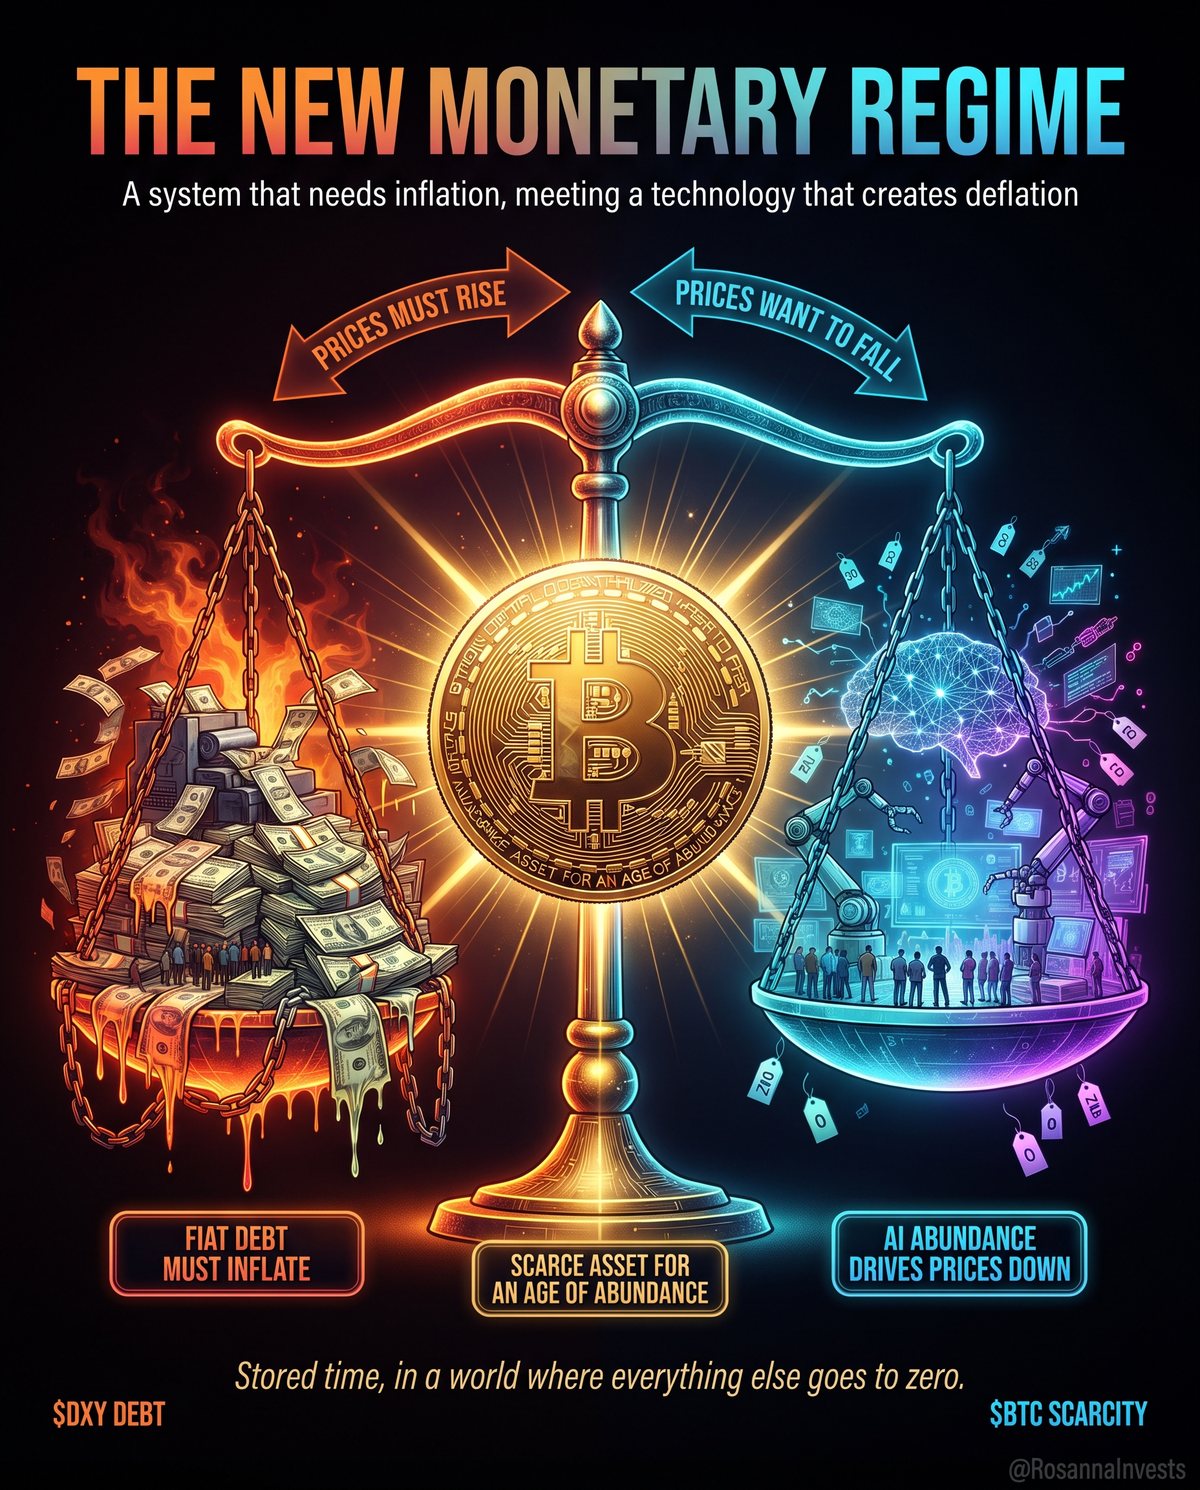
That’s the whole argument. AI lowers prices. Bitcoin is scarce.
For roughly four decades beginning in the early 1980s, much of the developed world operated inside a remarkably favorable disinflationary environment. Inflation fell from the extremes of the 1970s and early 1980s. Interest rates trended lower over long stretches. Globalization expanded access to lower-cost labor and production. Credit deepened. Financial assets benefited from declining discount rates, and governments, households and companies learned to operate with larger debt loads because the cost of carrying debt often became progressively easier to refinance. That period was not uniform, and it contained recessions, crises and inflation scares, but one assumption became deeply embedded in financial behavior: when stress became severe, lower rates and easier financial conditions were usually available somewhere in the response.
The debt accumulated under that architecture did not disappear when the rate environment changed. That is the first pressure shaping the regime now. Debt is a nominal promise. If prices and nominal incomes fall broadly while the amount owed remains fixed, the real burden of the liability rises. That arithmetic applies to households and companies, and at sovereign scale it becomes a constraint on fiscal and monetary policy. Higher rates can suppress demand and inflation, but they also raise the cost of refinancing a large stock of public debt as older securities mature. Falling nominal GDP can improve purchasing power for a saver while simultaneously making an overleveraged borrower’s balance sheet harder to carry. Those are not moral statements. They are opposing positions on the same contract.
The United States is not an abstract example. In its February 2026 baseline, the Congressional Budget Office projected federal debt held by the public rising from roughly 101 percent of GDP in 2026 to 120 percent in 2036, while net federal interest outlays more than double from about $1.0 trillion to $2.1 trillion. Those are projections, not destiny, and policy can change them. The importance is the sensitivity they reveal. The larger the debt stock, the more consequential the price of money becomes to the fiscal accounts. Research at the Bank for International Settlements has begun examining the same interaction explicitly: high sovereign debt can narrow fiscal space, complicate monetary transmission and increase the fiscal cost of sufficiently restrictive monetary policy. Fiscal dominance is not a switch that suddenly flips. It is a spectrum of constraints. A central bank can remain legally independent while the economic consequences of its interest-rate choices become increasingly entangled with the government’s financing burden.
This is why I describe the modern system as having a structural preference for nominal growth. I am not saying central banks can select any inflation rate they want, or that every deficit is monetized, or that every increase in the monetary base becomes consumer-price inflation. Those claims would be too simple. Real growth, productivity, taxes, spending, credit demand, banking behavior, demographics, regulation, exchange rates and velocity all matter. Governments can also reduce spending, raise revenue, restructure liabilities or simply tolerate financial pain. The point is narrower. A highly indebted system has difficulty tolerating prolonged broad deflation because deflation increases the real weight of fixed nominal claims. As the stock of those claims grows, political and financial pressure tends to favor some combination of nominal growth, sufficient liquidity, lower real financing costs or policies that keep the debt serviceable.
That is also why inflation and debasement need to be separated. CPI inflation measures changes in the price of a defined basket of consumer goods and services. It is useful, but it does not answer every question a saver cares about. A person can live through moderate measured consumer inflation while houses, productive businesses, gold or other scarce assets become much more expensive relative to cash. The monetary unit can lose ground against capital even when the grocery bill is not rising at crisis rates. I use structural debasement to describe that broader pressure: the persistent institutional tendency for nominal claims to expand faster than the system can comfortably extinguish them through real growth, taxation, repayment or default. The adjustment can show up in consumer prices, asset prices, negative real rates, financial repression, exchange rates or some combination. The mechanism matters more than the slogan. Debasement is not a single policy announcement. It is what happens when the claims keep multiplying and the system searches for a way to reconcile them with the real economy underneath.
In my conversation with Jeff Booth on my podcast, The RO Show, he compressed his thesis into one sentence: “prices fall to the marginal cost of production.” He was describing the directional pressure of competition and technology, not promising that every price in every market goes to zero. The important point is that productivity should allow more output to be produced from less input.
Technology enters from the other direction. The purpose of technology is not to make things more expensive. It is to produce more output from fewer scarce inputs. Mechanization reduced the amount of human labor required for many physical tasks. Computing collapsed the cost of calculation. Networks collapsed the cost of distributing information. Software turned processes that once required buildings, paper and clerical staffs into code. Artificial intelligence may push that process into categories of cognitive work that had previously remained expensive because intelligence itself was scarce. Drafting, coding, translation, analysis, design, customer service and research can increasingly be reproduced at a marginal cost far below the historical cost of the human labor they once required.
The effect will not be uniformly deflationary in every period. Building the AI economy is extraordinarily capital intensive. It requires semiconductors, data centers, transmission lines, transformers, cooling systems, land, energy and skilled labor. Those inputs are scarce. A sufficiently large investment boom can raise the price of the very resources needed to create future abundance. That is why I think of AI as potentially inflationary in construction and deflationary in consequence. The buildout can bid up scarce physical constraints even as the technology produced by that buildout lowers the cost of delivering intelligence and increases output per worker.
The cost compression is already visible inside AI itself. The OECD reported that its quality-adjusted price index for text-to-text models fell by nearly eighty percent between January 2024 and April 2026 while capabilities continued to improve. That does not mean the effective cost of every AI task fell eighty percent or that macroeconomic productivity automatically follows. Agents can consume far more tokens, companies have to reorganize around the tools, and complementary investments take time. But the direction of technological competition is unmistakable. More capability is being delivered for less unit cost. In a competitive economy, some part of that productivity gain should eventually appear as lower real prices, higher real wages, higher profits or some combination of all three.
This is the divergence that matters. Technology pushes toward abundance. A highly indebted financial system remains dependent on enough nominal income, cash flow and asset value to service a very large stock of nominal liabilities. One force keeps reducing the real cost of producing things. The other cannot comfortably allow all of that productivity to express itself as broad nominal deflation.
Bitcoin did not create that tension. Bitcoin is the monetary solution to it.
The productive economy can become more abundant without requiring the monetary asset used to store value to become more abundant as well. That distinction sounds obvious only because we have spent so long treating the properties of money and the properties of production as though they had to move together. They do not. If AI allows one hour of work to produce what once required ten, society is wealthier. If competition passes some of that gain to consumers, prices should fall in real terms. That is not an economic failure. It is the dividend of progress. The saver should be able to participate in it.
Bitcoin gives that increasingly productive economy a scarce monetary denominator. Its supply schedule does not expand because productivity rises. It does not expand because the price rises. It does not expand because a government needs cheaper financing, a banking system needs more liquidity, or a recession creates political pressure for accommodation. Most important, the rule is not administered by a central issuer that can decide the circumstances now justify an exception. Scarcity and decentralization have to be considered together. A scarce asset controlled by one company is scarce until the company changes the rule. A scarce monetary asset controlled by a government is scarce until policy changes. Bitcoin is different because the monetary rule is enforced across a decentralized network. The supply constraint is credible precisely because nobody owns the pen.
That is why I do not think of Bitcoin primarily as an inflation hedge. Inflation is one possible symptom of the larger monetary problem. The deeper issue is the relationship between an elastic system of nominal claims and a productive economy becoming more capable of abundance. Bitcoin separates those questions. Goods can become abundant. Software can become abundant. Intelligence can become dramatically cheaper. The monetary reserve does not also have to become abundant.
Abundance in production. Scarcity in money. Bitcoin makes both possible.
This is also where economic freedom enters the argument, but I mean freedom in a precise monetary sense rather than as a slogan. If money is stored time and wealth is stored choice, then economic freedom is the ability to preserve and direct a meaningful share of those choices across time. A saver who delays consumption is making a claim on the future. The quality of the money determines how dependent that future claim is on somebody else’s discretion. Bitcoin does not eliminate law, taxes, regulation, institutions or the need for human trust. It does something narrower and, in monetary terms, profound: it allows the saver to hold a reserve asset whose base supply cannot be unilaterally expanded by the institution that benefits from expansion. Monetary freedom is not the absence of every external constraint. It is the ability to carry stored time forward without requiring an issuer to preserve the scarcity of the unit for you.
This framework also explains why Bitcoin does not need technological or institutional failure in order to succeed. The thesis may become stronger if AI succeeds spectacularly. A world of rapidly increasing productivity does not need artificially scarce goods. It needs abundant goods. But the more effectively technology manufactures abundance, the more useful a reliably scarce monetary denominator can become for measuring and storing claims on that abundance. Bitcoin is not valuable because everything else has to collapse. It is valuable because productive abundance and monetary scarcity can coexist for the first time in a digitally native system at global scale.
The next stage is capital markets. Once an inelastic monetary asset exists inside an elastic fiat financial system, traditional finance begins building claims around it. Equity, debt, preferred stock, convertibles, warrants, ETFs, options, futures and credit can all be created in theoretically flexible amounts around an asset whose ultimate base supply does not respond. Some of that financial engineering will improve access and capital efficiency. Some will create genuine value. Some will create leverage, fragility and dilution. Some promoters will attach Bitcoin to a security and assume the word itself justifies the price. It does not. Bitcoin may be scarce. The securities built around Bitcoin are not. The next buyers of that scarcity may not be people at all. An economy where agents create and settle value at machine speed will need a reserve whose rules don’t wait for a meeting.
That is why the next era of Bitcoin will not be understood by studying Bitcoin alone. It has to be understood through money, debt, technology and capital markets. The first era asked what Bitcoin was. The next asks what happens when a decentralized scarce monetary asset is inserted into a world built on elastic credit, large nominal liabilities and rapidly falling technological costs. That is the monetary regime I believe we are entering.