The AI power value chain: fuel to rack
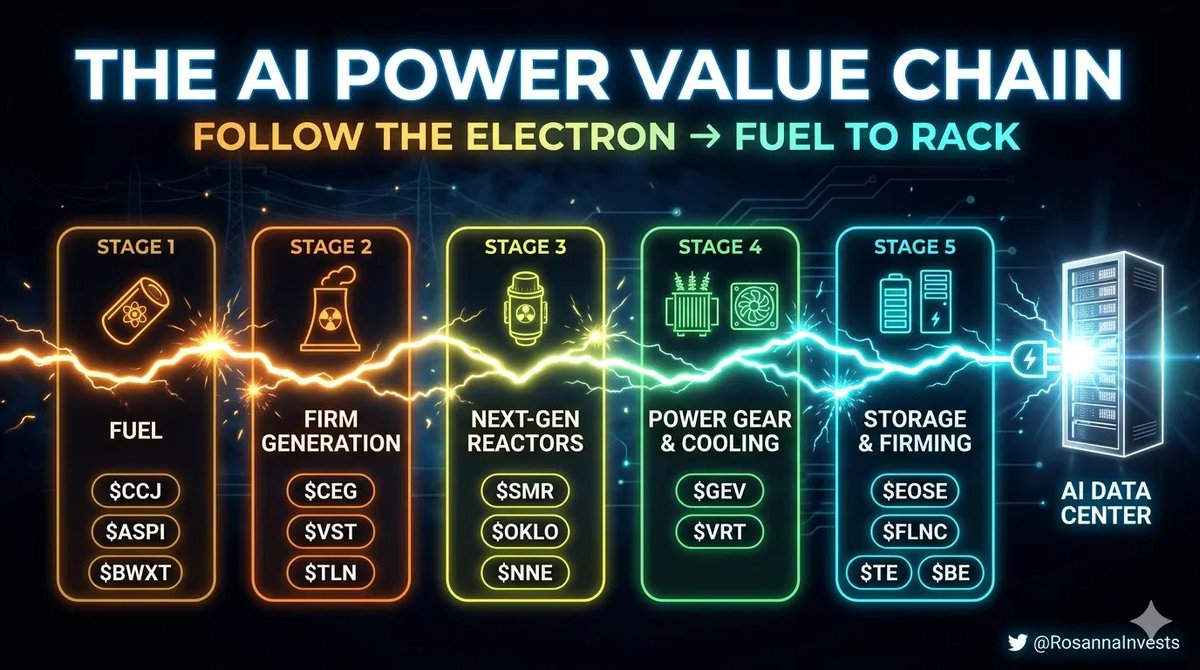
The AI power value chain, fuel to rack. Five stages, and every one is a bottleneck somebody owns.
Fuel comes first. Uranium demand is a decade contract, not a trade. CCJ and BWXT sit at the front of the chain, where the clock is measured in reactors and long-term procurement.
Firm generation is the next gate. CEG, VST and TLN own the megawatts data centers can actually sign for. Intermittent power is not enough when a cluster needs to run continuously.
Then comes transmission and the energized site: substations, interconnects and cooling. The scarce asset is not a GPU sitting in a catalog; it is capacity that survived the queue and can be turned on.
Finally, the rack converts power into revenue. Every stage is capex-heavy and financing-sensitive, so watch contracts, commissioning dates and working capital—not just the headline AI demand.
The investment case is simple but not risk-free: demand can be delayed, projects can be repriced and labor costs can squeeze margins. Still, physical bottlenecks tend to get paid before the final application layer. DYOR. Not FA.